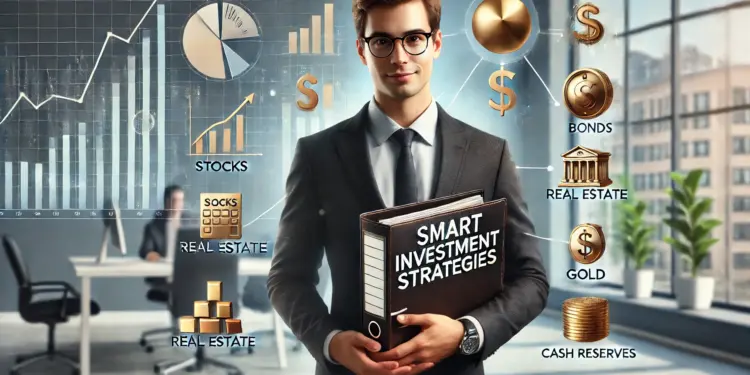
Navigating financial markets requires a clear roadmap, especially as global economic dynamics continue to shift rapidly. Managing personal wealth is no longer simply about buying a few stocks or depositing money into a fixed savings account. Instead, modern financial success depends on building an adaptable framework that aligns long-term capital growth with personal lifestyle objectives. By combining strategic asset allocation, risk mitigation techniques, and lifestyle-oriented planning, investors can establish a resilient foundation capable of withstanding market volatility while sustaining lifelong financial freedom.
1. Understanding the Core Foundations of Modern Portfolio Theory
At the heart of any sophisticated investment strategy lies Modern Portfolio Theory (MPT). Pioneered by Harry Markowitz, this mathematical framework demonstrates how an investor can construct an optimal portfolio to maximize expected return for a given level of risk. The primary premise is that an asset’s risk and return should not be assessed in isolation, but by how it impacts the overall portfolio’s risk and return characteristics.
The Role of Diversification and Correlation
Diversification is frequently described as the only “free lunch” in finance. By spreading capital across multiple asset classes such as equities, fixed income, real estate, and commodities investors reduce their exposure to the idiosyncratic risks associated with any single security.
-
Positive vs. Negative Correlation: Assets that move in opposite or uncorrelated directions help smooth out portfolio volatility over time. When stock markets experience a downturn, high-quality bonds or defensive commodities often hold their value or appreciate, preserving capital.
-
The Efficient Frontier: This represents the set of optimal portfolios that offer the highest expected return for a defined level of risk. Portfolios falling below the efficient frontier are sub-optimal because they do not provide enough return for the degree of risk taken.
Risk-Adjusted Returns
Focusing solely on raw percentage returns is a common mistake made by inexperienced investors. Sophisticated wealth management evaluates performance through risk-adjusted metrics:
-
Sharpe Ratio: Measures the excess return per unit of total risk (standard deviation). A higher Sharpe ratio indicates better compensation for the volatility endured.
-
Sortino Ratio: Focuses exclusively on downside volatility, providing a clearer picture of how well a portfolio protects against negative price swings.
-
Maximum Drawdown: Assesses the largest peak-to-trough decline experienced by a portfolio, offering insight into potential capital loss during severe market crashes.
2. Dynamic Asset Allocation Models for Long-Term Growth
Asset allocation dictates the vast majority of long-term investment performance. Rather than relying on static rules of thumb, modern investors utilize dynamic frameworks that adapt to changing macroeconomic environments and personal life stages.
Core-Satellite Strategy
A popular and practical structure for modern investors is the Core-Satellite approach. This model divides capital into two primary segments:
A. The Core Segment (70% – 80%): Consists of low-cost, broad-market index funds, exchange-traded funds (ETFs), or high-grade sovereign bonds. This foundation provides steady, market-matching returns with minimal management fees and low turnover.
B. The Satellite Segment (20% – 30%): Consists of active management plays, individual growth stocks, sector-specific ETFs, venture capital, or emerging digital assets. This portion aims to generate alpha (excess returns) without exposing the entire portfolio to catastrophic loss.
+-------------------------------------------------------+
|                 TOTAL PORTFOLIO                      |
+-------------------------------------------------------+
|                                                       |
|   [CORE SEGMENT: 70% - 80%]                           |
|   - Broad-Market Index ETFs                           |
|   - Global Equities & Sovereign Bonds                 |
|   - Low Fee, Passive Capital Accumulation             |
|                                                       |
|   -------------------------------------------------   |
|                                                       |
|   [SATELLITE SEGMENT: 20% - 30%]                      |
|   - Individual High-Growth Equities                   |
|   - Real Estate & Sector-Specific ETFs                |
|   - Tactical / Alternative Assets                     |
|                                                       |
+-------------------------------------------------------+
Strategic vs. Tactical Asset Allocation
Strategic allocation establishes long-term target weights for each asset class based on historical returns and risk tolerance. In contrast, tactical asset allocation allows for temporary shifts away from the strategic mix to capitalize on short-term market inefficiencies or economic cycles.

For instance, if equities become severely undervalued during a market panic, a tactical adjustment might temporarily increase equity exposure above target levels to capture the eventual recovery.
3. Integrating Life Stages with Portfolio Design
An effective investment strategy cannot exist in a vacuum; it must evolve alongside an individual’s career trajectory, family commitments, and retirement targets. Life-stage investing aligns asset allocation with human capital an individual’s total future earning potential.
The Accumulation Phase (Early to Mid Career)
During the early earning years, human capital is at its peak, while financial capital is relatively low. Investors in this stage can afford to take higher investment risks because they have decades to recover from market downturns.
-
Asset Mix: Focus heavily on capital appreciation through equities, technology sectors, and emerging market opportunities.
-
Strategy: Systematic monthly investments using dollar-cost averaging (DCA) to buy more shares when prices are low and fewer when prices are high.
The Consolidation Phase (Peak Earning Years)
As investors reach their mid-40s and 50s, financial capital increases, but time horizons shorten. Protecting accumulated wealth becomes as important as growing it.
-
Asset Mix: Gradually introduce income-generating assets, dividend-paying stocks, real estate investment trusts (REITs), and investment-grade corporate debt.
-
Strategy: Shift focus from aggressive speculation toward risk management, estate planning, and tax optimization.
The Distribution Phase (Retirement)
In retirement, human capital drops to zero, and the portfolio must generate reliable cash flow to fund daily living expenses.
-
Asset Mix: High allocation to capital preservation vehicles, short-duration bonds, dividend aristocrats, and cash reserves.
-
Strategy: Implement sustainable withdrawal rates (such as the 4% rule) while maintaining enough growth exposure to prevent inflation from eroding purchasing power.
4. Comprehensive Step-by-Step Modern Wealth Strategy
Executing a modern investment plan requires a structured, repeatable process. Skipping crucial steps often leads to emotional decision-making, excessive tax burdens, or unmanaged downside risk.
5. Tactical Risk Management and Portfolio Protection
Preserving wealth over long horizons requires robust defensive protocols. Ignoring downside management can erase years of compounding in a matter of weeks during systemic financial crises.
Hedging Against Systemic Risk
While diversification handles unsystematic (company-specific) risk, systemic market downturns require active defensive measures:
-
Options Overlay Strategies: Utilizing put options can act as insurance policies against sharp equity market drops.
-
Tactical Cash Positions: Holding cash or short-term treasury bills during times of extreme market overvaluation provides liquidity to buy distressed assets when prices bottom out.
-
Alternative Real Assets: Allocating to physical commodities, gold, and infrastructure assets shields portfolios from unexpected inflationary spikes.
The Mechanics of Systematic Rebalancing
When an asset class performs exceptionally well, it naturally grows to occupy a larger percentage of the overall portfolio than intended. This increases total portfolio risk.
A. Calendar-Based Rebalancing: Reviewing and adjusting portfolio weights at fixed intervals (e.g., every 6 or 12 months).
B. Threshold-Based Rebalancing: Adjusting portfolio weights whenever an asset class drifts by a set percentage (e.g., ±5%) from its target allocation.
By selling a portion of appreciated assets and buying underperforming ones, systematic rebalancing forces investors to adhere to the timeless rule of investing: buy low, sell high.
6. Sustainable Income Generation in Modern Markets
For modern portfolio lifestyle management, generating predictable cash flow without depleting principal is the ultimate objective. Investors rely on a mix of traditional and modern yield strategies to maintain financial independence.
Comparison of Popular Yield-Generating Assets
| Asset Class | Primary Advantage | Main Risk Factor | Income Yield Potential |
| Dividend Aristocrats | Rising payouts over time | Equity market volatility | Moderate (2% – 4%) |
| Corporate Bonds | Fixed interest payment priority | Default / Interest rate risk | Moderate (4% – 6%) |
| Real Estate (REITs) | Inflation-hedged tangible backing | Property market downturns | High (5% – 8%) |
| High-Yield Treasury Bills | Backed by sovereign guarantee | Reinvestment / Inflation risk | Low to Moderate (3% – 5%) |
7. Essential Guidelines for Portfolio Optimization
To maintain long-term performance and minimize costly mistakes, modern wealth builders should follow these standardized structural practices:
A. Conduct thorough fundamental analysis on every single asset before allocating capital.
B. Minimize drag from high investment fees, expense ratios, and turnover costs.
C. Utilize tax-advantaged account structures like IRAs, 401(k)s, or regional equivalents.
D. Maintain strict emotional discipline by automating monthly deposits and rebalancing steps.
E. Review personal insurance coverage to protect investment capital from liability claims.
F. Align portfolio decisions with real-world spending needs and long-term liquidity goals.
G. Adjust assumptions periodically to reflect changes in inflation rates and life expectancy.
8. Managing Psychological Biases in Wealth Building
Behavioral finance shows that investor emotion is often the single biggest threat to portfolio survival. Cognitive biases frequently lead individuals to abandon sound plans at the worst possible times.
Loss Aversion
Psychologically, the pain of losing $\$1,000$ is twice as intense as the joy of gaining $\$1,000$. This bias causes investors to hold onto losing positions too long in hopes of breaking even, or to panic-sell at market bottoms out of fear of further losses.
Herding Behavior and FOMO
The “Fear Of Missing Out” drives investors to chase speculative bubbles near market tops. Recognizing herd mentality and maintaining a disciplined rules-based framework prevents purchasing overvalued assets right before severe corrections.
Confirmation Bias
Investors naturally seek out news and analysis that support their existing beliefs while ignoring warning signs. To combat this, elite portfolio managers deliberately seek out counter-arguments to test the validity of their investment thesis.
Conclusion
Building a sustainable investment strategy is an ongoing journey rather than a one-time event. By grounding your approach in Modern Portfolio Theory, structuring asset allocation around key life stages, enforcing strict risk management, and avoiding emotional pitfalls, you build a foundation designed for long-term growth. True financial success lies in designing a resilient portfolio that quietly powers your personal lifestyle goals, allowing your wealth to work for you through every market cycle.